Reading time: 8 minutes
An umbrella company does not sell a product; it sells a management service.
Its profitability, therefore, isn’t measured by a traditional sales margin, but rather by a combination of indicators specific to the industry: management fees, collection times, and financial reserves set aside on behalf of the contractors. Without the right tools, managing umbrella employment relies on disparate Excel spreadsheets that are updated manually and are never fully synchronized. This is a real headache for management and, above all, a constant source of errors.
Why Financial Management Is Unique in the Umbrella Employment Industry
In most service companies, financial performance is measured by traditional metrics: turnover, gross margin, and customer payment terms. An umbrella company must track these metrics but also include others specific to its line of business.
Revenue billed to end customers passes through the umbrella company, but it does not belong to the umbrella company.
Its actual compensation corresponds to the management fees deducted from this turnover, before the salary is paid to the contractor. Managing the financial performance of an umbrella company therefore means managing a cash flow that passes almost entirely through the company, without ever truly belonging to it. One must also take into account the mandatory financial reserve that must be set aside for each contractor, which is separate from the umbrella company’s own cash flow.
With a business model like this, Excel spreadsheets quickly reach their limits.
As soon as the number of transactions increases, manually reconciling activity accounts, management fees, and reserves becomes a full-time task, with the risk of error increasing in proportion to the volume processed.
Key Metrics to Track When Managing an Umbrella Company
Reliable financial management relies on a limited number of metrics that are monitored regularly. Here are the five metrics that form the basis of the umbrella company dashboard.
Management Fees
This is the most fundamental indicator of the business model and the primary driver of profitability: the portion of turnover billed by contractors that the umbrella company retains—before paying salaries—to fund its operations (administrative staff, tools, insurance, and financial guarantees).
Management fees are easy to calculate. They represent a percentage of the turnover billed by the contractors or a fixed amount regardless of the turnover billed. These fees may be capped.
Management Fees Rate = (Management Fees Collected / Turnover Billed by Contractors) × 100
The rate varies from company to company and depending on the services included in the package. We discuss this topic in detail in the dedicated article below.
We explain how to calculate and manage management fees in our dedicated article: Management Fees in Umbrella Employment: How to Calculate and Manage Your Margin.
The average payment period for customers
This is the average time between issuing a customer invoice and actually receiving payment. In some umbrella companies, this timeframe has a direct impact: it is the receipt of payment for the customer invoice that enables the umbrella company to pay the contractor’s salary. Even a slight increase in the average payment period—by just a few days—can be enough to create cash flow strain, particularly for a umbrella company where several major clients all pay at the end of the month.
Average payment period = (Accounts receivable / Turnover billed during the period) × Number of days in the period
An average payment period that consistently exceeds the contractual payment terms (30 or 45 days, for example) indicates a collection issue that needs to be addressed before it becomes systemic.
Average revenue per contractor and the share of active contractors
Two volume indicators that determine the predictability of the umbrella company’s overall revenue. Average revenue per contractor makes it possible to quickly identify a decline in activity in part of the portfolio before it leads to cash flow pressure. The share of active contractors—that is, the percentage of contractors who actually bill during the period—complements this analysis: a declining rate may signal a billing issue, a sales problem on the contractors’ side, or a loss of assignments.
The consolidated financial reserve
The total amount of reserves set aside for all contractors—generally a few percentage points of each contractor’s revenue—is replenished each month and returned at the end of the contract or used to smooth out compensation during slow months. These funds belong to the contractors, not to the umbrella company: rigorous financial management clearly separates them from the company’s own cash flow to prevent accounting confusion from masking a real solvency problem or, conversely, from creating the false appearance of a cash flow crunch.
Taken individually, each of these five indicators tells part of the story. When tracked together on a regular basis, they make it possible to anticipate cash flow strain rather than simply having to deal with it .
Implementing Monthly Monitoring: The Method
Financial management is only valuable if it is conducted on a regular basis. A monthly review, organized into three stages, is sufficient for most umbrella companies:
- Data consolidation: monthly billing, collections, management fees deducted, reserves set aside. Ideally automated rather than re-entered from multiple files.
- Analyzing variances: comparing the five indicators with the previous month and with the projected budget to identify deviations before they become entrenched.
- Decision and Action: Adjust customer collection efforts if the average payment period worsens; review the management fee rate for new contracts; alert HR if the share of active contractors declines.
This monthly pace is sustainable in the long run only if consolidation can be achieved using a centralized tool.
Improving Billing Reliability to Secure Cash Flow
Billing is the second pillar of financial management: it triggers cash collection and, therefore, the umbrella company’s ability to pay its contractors’ salaries on time. Manual invoicing, based on activity reports collected via email or Excel files, increases processing times and the risk of errors. These are two factors that directly worsen the average payment cycle.
In our article, “Invoicing for Umbrella Employement Services: How to Automate and Streamline Your Process with an ERP,” we explain how to automate this process and make it more reliable.
How an ERP System Changes Financial Management at an Umbrella Company
The most tangible difference between managing an umbrella company using Excel and managing it with a dedicated ERP system lies in the reliability of the available data and its real-time availability. When management fees, billing, and financial reserves are centralized in the same system, the manager can view an up-to-date financial overview at any time. No more waiting for a manual month-end consolidation!
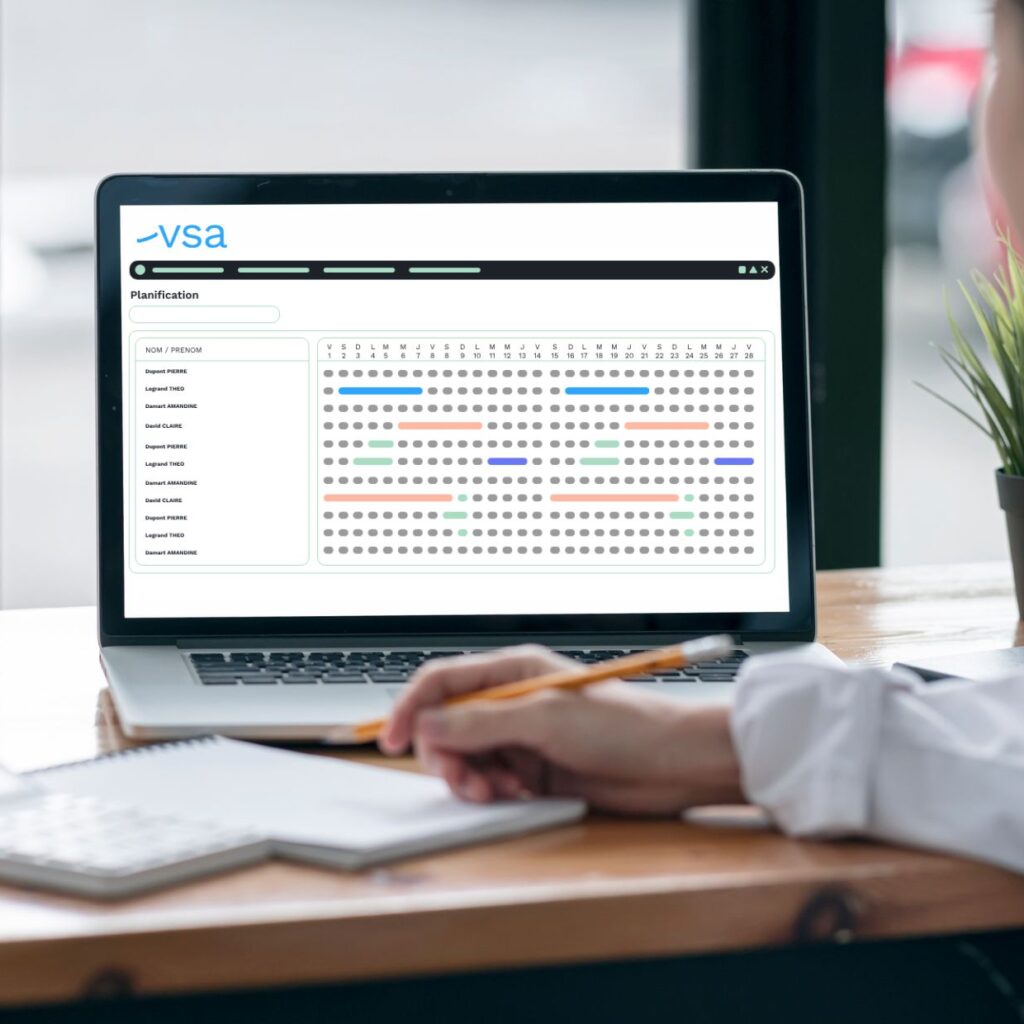
This is the experience shared by several umbrella companies that use VSPortage: Centralizing billing, payroll, and expense data in a single tool transforms management tasks—which were previously scattered across multiple files—into financial reports that can be accessed at any time, without having to wait for accounting deadlines.
In practical terms, this changes three things about how an umbrella company executive manages their business:
- The separation between the financial reserve for contractors and the umbrella company’s own cash reserves is structurally ensured by the system, rather than depending on the accuracy of a separate file.
- The five metrics (management fee, average payment time, turnover per contractor, share of active contractors, and consolidated reserve) are calculated automatically based on the same billing and payroll data, without the need for re-entry or the risk of discrepancies between different files.
- The monthly review described above no longer requires a manual consolidation phase: discrepancies are visible in the various reports, which frees up time for decision-making and action.
VSPortage: Centralized Financial Management for Your Umbrella Company
VSPortage combines invoicing, payroll, management fees, and tracking of your contractors’ financial reserves into a single tool. Your financial performance metrics (management fees, average payment terms, turnover per contractor) are available in real time, without the need for manual consolidation.
FAQ – Frequently Asked Questions About the Financial Management of an Umbrella Company
How often should an umbrella company monitor its financial metrics?
A monthly review is the recommended minimum, aligned with the umbrella company’s billing and payroll cycle. The average payment period and cash flow status may warrant more frequent (weekly) monitoring during periods of strong growth in the number of contractors, when cash flow needs change rapidly.
How do management fees affect umbrella company net margin?
Management fees, deducted from the contractors’ turnover before salary payments, are intended to cover all overhead costs (internal salaries, tools, insurance, and financial guarantees). If your overhead costs rise faster than the number of contractors, you risk seeing your net margin decline rapidly.
Why separate the financial reserve for contractors from the umbrella company’s cash balance?
These funds belong contractually to the employees, not to the umbrella company. Confusing them with the umbrella company’s cash on hand exposes the umbrella company to a twofold risk: underestimating actual cash flow needs if the reserves are counted as available cash, or overestimating financial difficulties if they are not clearly distinguished in the financial reports.